Running a small business comes with a wide range of costs. You may pay for software, equipment, professional services, advertising, business travel, insurance, phone bills and many other things simply to keep the business operating.
Some of these costs may qualify as allowable business expenses, meaning they can be deducted when calculating taxable profit. However, not every payment made by a business can automatically be treated as an allowable expense. The tax treatment can depend on the type of expense, how it is used and the structure of the business.
This guide explains the main small business expenses you may be able to claim in the UK, how mixed business and personal costs are treated, which expenses require particular care and what records you should keep.
Table of Contents
ToggleThe principles covered here can apply to sole traders, partnerships and limited companies, but the tax rules are not identical for every type of business. If you need broader support with your business finances, our Small Business Accountants in London provide accounting and tax support tailored to growing businesses.
Small Business Expense Checklist: What Can You Claim?
| Expense | Potentially claimable? | What to check |
|---|---|---|
|
Office stationery |
Yes, where for the business |
Keep invoices / receipts |
|
Business software |
Generally, where business-related |
Check for private use |
|
Business phone |
Potentially |
Separate business and private use where required |
|
Home internet
|
Potentially |
Consider business use and the applicable method
|
|
Laptop
|
Potentially |
Check capital/revenue treatment and private use
|
|
Business mileage
|
Potentially
|
Journey must qualify; keep mileage records
|
|
Normal commuting
|
Generally no
|
Home-to-permanent-workplace rules
|
|
Business insurance
|
Potentially |
Policy must relate to the business
|
|
Accountant fees |
Potentially
|
Consider what the professional service relates to
|
|
Ordinary work clothing
|
Generally no
|
Clothing rules can be restrictive
|
|
Business meals
|
Sometimes
|
Depends on the circumstances and qualifying travel
|
|
Fines and penalties
|
Generally no
|
Business purpose does not normally make a penalty deductible
|
What Is an Allowable Business Expense?
An allowable business expense is a business cost that you can claim against your income when calculating taxable profit, provided it meets the relevant tax rules.
For a sole trader, allowable expenses are deducted from business income when calculating taxable profit. For example, if a sole trader has £50,000 of business income and £10,000 of allowable expenses, the taxable profit before other adjustments would be £40,000.
For a limited company, qualifying costs of running the business can generally be taken into account when calculating the company’s taxable profit for Corporation Tax purposes.
This does not mean every cost connected with the business is automatically deductible.
The key questions are:
- What was the expense for?
- Was it incurred for the business?
- Does the relevant tax rule allow the expense?
- Is there any personal use that needs to be excluded?
- Do you have appropriate records to support the claim?
These questions become particularly important when an expense has both business and personal elements.
Business Expense or Personal Expense?
One of the most important principles for small businesses is separating business expenditure from private expenditure.
A cost does not become an allowable expense simply because you paid for it from a business bank account or used it occasionally while working.
For example, suppose your mobile phone costs £600 during the year and you use it for both business and personal purposes. You cannot simply treat the entire £600 as a business expense. You need to identify the part that relates to business use.
The same principle can apply to:
- Mobile phones
- Internet connections
- Vehicles
- Home working costs
- Computers and other equipment
- Other assets or services with mixed use
This distinction is important because claiming private expenditure as a business cost can result in an incorrect tax calculation.
What Are the Most Common Small Business Expenses?
The expenses a small business incurs will depend largely on the type of work it does. A consultant working from home may have costs for software, professional fees and internet services, while a retailer may spend more on stock, premises and packaging. A construction business may have very different expenses again, such as tools, materials, vehicles and protective equipment.
There is therefore no single list of business expenses that applies to every small business.
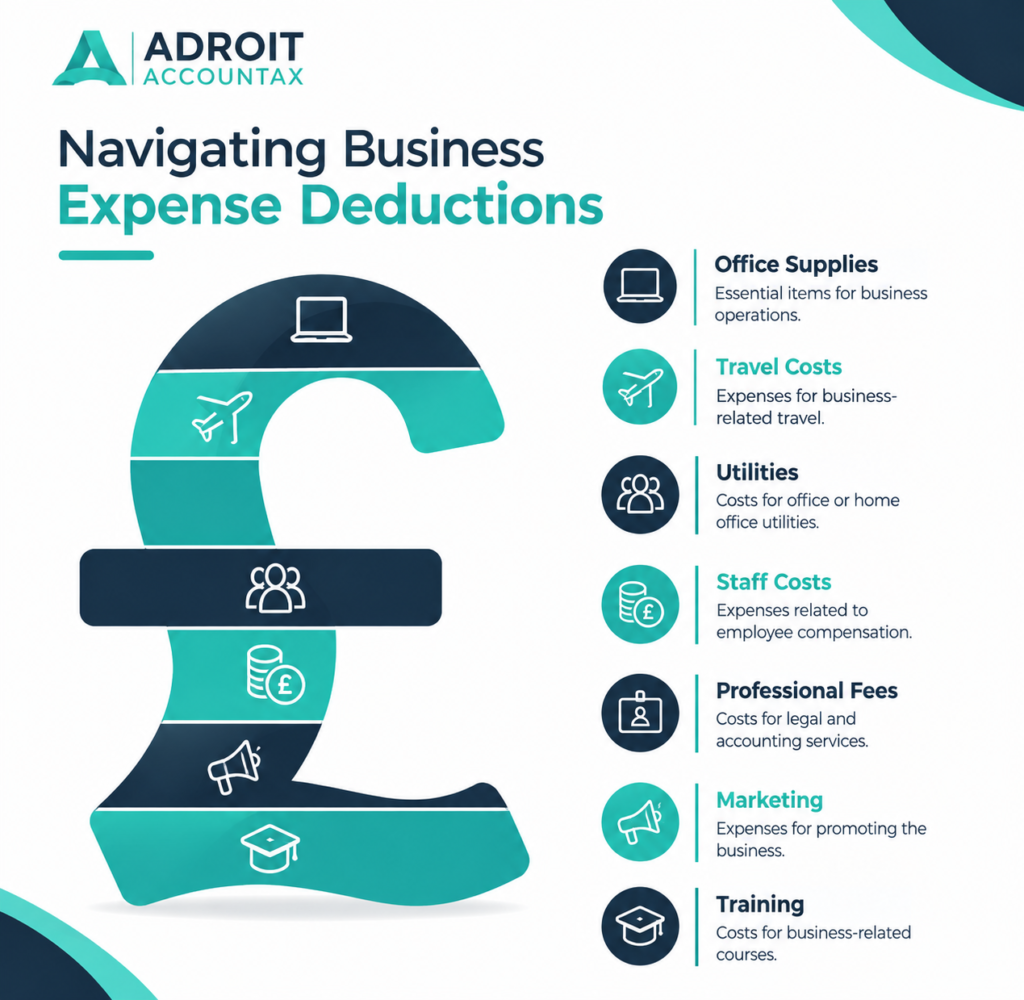
However, many UK businesses encounter similar categories of costs. The following are some of the most common expenses that may qualify for tax relief, provided they meet the relevant tax rules.
1. Office Costs and Stationery
Everyday office costs can add up quickly, particularly for businesses that operate from commercial premises or rely heavily on administrative work.
Common office expenses can include:
- Stationery and office supplies
- Printing and printer ink
- Postage and delivery costs
- Business telephone costs
- Business internet costs
- Certain office software
- Office rent
- Business premises running costs
- Other consumables used in the day-to-day running of the business
For example, a small consultancy might regularly purchase printer paper, stationery and postage for sending documents to clients. These are very different from purchasing a high-value computer or specialist piece of equipment, where the tax treatment may need to be considered separately.
What about office equipment?
It is important not to assume that every item purchased for an office is treated in the same way.
A £30 box of stationery is a routine business cost, whereas a £2,000 computer, printer or piece of specialist equipment may be subject to different tax rules.
The treatment can depend on the nature of the asset, how it is used and the rules applying to the business. If equipment is also used privately, the personal use may also need to be considered.
Keeping invoices and purchase records for office equipment can help establish what was bought, when it was purchased and how it is used.
If you need help keeping business transactions organised, our Bookkeeping Services in London can help maintain accurate financial records throughout the year.
2. Business Software and Subscriptions
Software is now an essential operating cost for many small businesses. Whether you work from home, run an online business or operate from commercial premises, you may rely on several digital services to keep the business running.
Common examples include:
- Accounting software
- Customer relationship management (CRM) systems
- Project management software
- Cloud storage
- Cybersecurity software
- Website hosting
- Design and editing software
- Video conferencing and communication platforms
- Industry-specific software
- Online business tools and subscriptions
Where software is purchased or subscribed to for a genuine business purpose, the cost may qualify for tax relief under the relevant rules.
For example, a graphic designer may pay for professional design software to complete client projects, while an online retailer may use accounting, stock-management and e-commerce software as part of its day-to-day operations.
What if software is used personally as well?
This is where the position can become less straightforward.
If a subscription is used for both business and personal purposes, you should consider whether the private element needs to be excluded rather than automatically claiming the entire cost.
For example, a software subscription used exclusively to manage customer accounts has a clear business purpose. A subscription used partly for private activities may require a different approach.
It is also worth keeping records of recurring subscriptions. Monthly software payments can be easy to overlook, particularly when a business has several different services operating at the same time.
3. Phone and Internet Costs
Phone and internet costs are particularly common for freelancers, consultants, contractors and businesses that operate partly or entirely from home.
The tax treatment can be more straightforward where a service is used exclusively for business. However, many small business owners use the same phone, broadband connection or other communications services for both work and private purposes.
In those circumstances, the business and personal elements need to be considered under the relevant tax rules.
Example: business and personal use
Suppose your annual phone and internet costs are:
- Total annual cost: £1,200
- Business use: 60%
- Illustrative business element: £720
The £720 figure is simply an example. You should not automatically claim 60% of your own phone or internet costs.
The business proportion should be based on a reasonable method that reflects your actual circumstances and the rules applying to the particular expense.
Keeping appropriate records can also make it easier to explain how the business element was calculated if you need to refer back to it later.
4. Professional and Accountancy Fees
Professional advice can be an important part of running a small business.
Depending on the nature of the business, costs may include:
- Accountancy and bookkeeping services
- Tax advice
- Business-related legal services
- Professional consultancy
- Surveyors
- Architects
- Other specialist professional services
The key issue is not simply whether you paid a professional. The purpose of the service matters.
For example, accountancy work relating to your business accounts may have a clear connection with the trade. A legal fee relating to a private matter would need to be considered differently.
The same principle applies to other professional services: you should consider what the advice or work was actually for before treating the cost as an allowable business expense.
If you need broader support with accounts, tax compliance or financial management, our Accounting Services in London provide support for businesses at different stages of growth.
5. Advertising and Marketing
Marketing is an important expense for many small businesses because attracting customers often requires ongoing investment.
Depending on the business, marketing and advertising costs may include:
- Website development and maintenance
- Search engine optimisation (SEO)
- Online advertising
- Social media advertising
- Printed marketing materials
- Business cards
- Advertising in newspapers, magazines or other publications
- Promotional materials
- Certain samples or promotional items
The important consideration is the purpose of the expenditure.
For example, paying for Google Ads to promote your services to potential customers has an obvious business purpose. Similarly, paying for a business website or professional marketing materials can be directly connected with promoting the trade.
However, businesses should be careful not to assume that every item described as “marketing” is automatically allowable. The nature and purpose of the expenditure still need to be considered.
Keeping marketing costs separately categorised can also help you understand how much your business is investing in areas such as advertising, customer acquisition and promotion.
6. Business Insurance
Insurance can be an important operating cost, particularly for businesses that provide professional services, employ staff, own business premises or work with customers on-site.
Depending on the nature of the business, insurance costs may include:
- Public liability insurance
- Professional indemnity insurance
- Business property insurance
- Insurance relating to business premises
- Other policies connected with business activities
For example, a consultant may need professional indemnity insurance, while a business operating from commercial premises may have insurance covering its property or business activities.
The specific policy and its purpose should still be considered before claiming the cost.
It is sensible to keep the insurance policy documents and invoices with your financial records so that you can demonstrate what the policy covered and why the expense was incurred.
7. Business Travel and Mileage
Business travel can be an allowable expense, but a journey being connected with your work does not automatically make every travel cost claimable.
Depending on the circumstances, qualifying business travel may include costs such as public transport, taxis, parking, hotel accommodation and business mileage. The key question is whether the journey qualifies as business travel rather than ordinary commuting or private travel.
For example, travelling to visit a client or another temporary workplace may qualify, whereas travelling between your home and a permanent workplace is generally treated differently.
If you use your own vehicle for business journeys, keep records showing the date, destination, purpose and business mileage. This provides evidence for your claim and makes it easier to calculate your allowable travel costs.
The rules around business mileage, vehicle costs, commuting, accommodation and other travel expenses can be more complicated than they first appear.
For the detailed rules and current mileage rates, see our guide to Business Mileage and Travel Expenses.
8. Working From Home Expenses
Business travel can be an allowable expense, but a journey being connected with your work does not automatically make every travel cost claimable.
Depending on the circumstances, qualifying business travel may include costs such as public transport, taxis, parking, hotel accommodation and business mileage. The key question is whether the journey qualifies as business travel rather than ordinary commuting or private travel.
For example, travelling to visit a client or another temporary workplace may qualify, whereas travelling between your home and a permanent workplace is generally treated differently.
If you use your own vehicle for business journeys, keep records showing the date, destination, purpose and business mileage. This provides evidence for your claim and makes it easier to calculate your allowable travel costs.
The rules around business mileage, vehicle costs, commuting, accommodation and other travel expenses can be more complicated than they first appear.
For the detailed rules and current mileage rates, see our guide to Business Mileage and Travel Expenses.
Book a consultation today
Discover how Adroit Accountax can support your business with reliable, professional accounting services.9. Business Equipment and Computers
Many small businesses need equipment to carry out their work.
This could include:
- Laptops and desktop computers
- Monitors
- Printers
- Cameras
- Specialist tools
- Machinery
- Office furniture
- Other equipment used in the business
The tax treatment of equipment can be different from ordinary day-to-day expenses.
For example, stationery purchased for £30 is a routine operating cost. A £2,000 computer that you keep and use in the business is a different type of expenditure and may be dealt with under the rules for equipment and capital allowances, depending on the business and accounting method.
For some businesses using the cash basis, qualifying equipment can be claimed as an allowable expense, while businesses using traditional accounting may need to consider capital allowances. There are also specific rules for vehicles and certain other assets.
What if you use business equipment personally?
If equipment is used for both business and private purposes, the personal use needs to be considered.
For example, if a laptop is purchased primarily for business work but is also regularly used for personal activities, you should not automatically assume that the entire cost receives business tax treatment.
The correct approach depends on the applicable rules and the circumstances of the purchase and use.
10. Stock, Materials and Goods for Resale
Businesses that sell products or manufacture goods can have significant costs relating to stock and materials.
Depending on the business, these may include:
- Goods purchased for resale
- Raw materials
- Components
- Packaging
- Product labels
- Manufacturing materials
- Other items used to make or supply products
For example, a small online clothing business may purchase garments from suppliers, packaging for customer orders and labels for its products. A tradesperson may purchase materials that are incorporated into work carried out for customers.
Keeping accurate records of purchases is particularly important where a business holds stock. The accounting treatment can involve stock values and the timing of costs, so simply treating every purchase as an immediate expense may not always give the correct result.
11. Staff Costs and Subcontractors
Employing people or using subcontractors can be a major expense for a growing business.
Depending on the circumstances, costs may include:
- Employee wages
- Employer National Insurance contributions
- Employer pension contributions
- Certain employee benefits
- Subcontractor payments
- Other qualifying employment-related costs
The treatment of employees and subcontractors is not identical, so businesses should make sure they understand the rules applying to the people they pay.
It is also important to keep appropriate payroll, invoice and payment records.
For subcontractors in particular, the business may need to consider whether specific rules apply to the work being carried out. In some industries, such as construction, additional tax rules can apply to payments made to subcontractors.
12. Training and Professional Development
Training can be an important investment for a small business, particularly when it helps the owner or employees maintain or improve skills relevant to the existing business.
Examples might include:
- Industry-specific training
- Professional courses
- Refresher training
- Technical training
- Business-related workshops
- Training needed to maintain professional knowledge
The purpose of the training matters.
Training that relates to the existing business may have a different tax treatment from training that is designed to start an entirely new trade or profession.
For that reason, it is useful to keep the course description, invoice and evidence of how the training relates to the business.
13. Business Bank Charges and Financial Costs
Small businesses can also incur various financial costs as part of their normal operations.
Depending on the circumstances, these may include:
- Business bank charges
- Overdraft charges
- Business credit card charges
- Interest on qualifying business borrowing
- Certain hire purchase interest
- Certain leasing costs
HMRC’s guidance for self-employed businesses specifically identifies business bank, overdraft and credit card charges, as well as certain interest and finance costs, as potential business expenses.
The precise treatment can depend on the type of finance and how the borrowing is used, so business owners should not assume that every interest payment is automatically deductible.
What If an Expense Is Used for Both Business and Personal Purposes?
Mixed-use expenses are one of the areas where small business owners can easily make mistakes.
A cost does not automatically become 100% deductible simply because it is useful to the business.
For example, consider a laptop purchased for £1,500.
If it is used for client work, accounting, emails and other business activities, there is an obvious business purpose. But if it is also used privately, the private element may need to be considered depending on the applicable tax rules.
The same issue can arise with:
- Cars and other vehicles
- Mobile phones
- Internet services
- Computers
- Home expenses
- Software subscriptions
- Other equipment
Can you simply claim a percentage?
Not always.
Where the relevant rules allow an expense to be apportioned, the calculation should have a reasonable basis.
For example, if a service has identifiable business and private use, you may need to determine the business proportion rather than simply claiming the whole cost.
However, some expenses raise more complicated questions because the expense itself may have both business and private purposes.
This is why the principle of “it’s used for work” is not always enough to determine whether a cost is allowable.
What Business Expenses Cannot You Claim?
Knowing what you can claim is only half of managing business expenses correctly. It is equally important to understand that some costs are not allowable, or may be subject to restrictions.
Common examples that require particular care include:
- Private or personal expenditure
- Ordinary journeys between home and a permanent workplace
- Fines and penalties for breaking the law
- Costs unrelated to the business
- Certain private legal or professional costs
- Ordinary clothing that is not qualifying workwear
- Personal entertainment
- Other expenditure that does not meet the relevant tax rules
For example, buying a suit to wear to ordinary business meetings does not automatically make the cost a business expense simply because you wear it while working. Likewise, a parking fine does not become an allowable expense because the vehicle was being used for business at the time.
HMRC specifically states that self-employed individuals cannot claim non-business travel costs, fines or penalty charges, or travel between home and work as allowable travel expenses.
The important point is that you should not try to turn a private expense into a business expense simply because there is some connection with your work.
Here is a small comparison of what is generally not a claimable expense.
| Expense | Generally allowable? | Why caution is needed |
|---|---|---|
|
Private expenditure
|
No |
Not incurred for the business
|
|
Ordinary commuting
|
Generally no
|
Home-to-permanent-workplace travel is treated differently
|
|
Ordinary clothing
|
Generally no
|
Wearing clothing for work does not automatically make it allowable
|
|
Client entertainment
|
Generally no for tax deduction
|
Entertainment has specific restrictions
|
|
Fines and penalties |
Generally no
|
A business purpose does not normally make a penalty deductible
|
|
Personal household spending
|
No |
Private costs should not be treated as business expenditure
|
|
Loan capital repayments
|
No as an interest expense
|
Capital repayment is different from interest
|
|
Personal subscriptions
|
Generally no
|
Business benefit alone may not be sufficient |
|
Private meals
|
Generally no
|
Ordinary living costs are different from qualifying business travel |
Can You Claim Meals as a Business Expense?
Meals are one of the business expenses that are most often misunderstood. You generally cannot claim your normal food costs simply because you are self-employed or were working that day.
However, food and accommodation costs can potentially be allowable when they arise from qualifying business travel. The treatment depends on the nature and circumstances of the journey.
For example, buying lunch during a normal working day is generally a personal living cost. A meal incurred as part of qualifying business travel may be treated differently.
The same distinction applies to business entertainment. Paying for a meal with a client or supplier does not automatically make the cost an allowable business expense.
If you regularly incur meals, subsistence or entertainment costs through your business, it is important to distinguish between personal food, qualifying travel expenses and business entertainment.
For the detailed rules, examples and exceptions, see our guide to Business Meals and Entertainment Expenses.
What Records Should You Keep for Business Expenses?
Good record keeping is not simply an administrative task. It gives you evidence to support your tax calculations and makes it easier to identify genuine business costs.
For self-employed businesses, HMRC requires records of business income and expenses and says records should be accurate and allow business transactions to be identified. Evidence can include receipts, bank statements, invoices and other supporting documents.
Useful records can include:
- Supplier invoices
- Receipts
- Bank statements
- Credit card statements
- Mileage records
- Contracts
- Subscription invoices
- Insurance documents
- Training invoices
- Records explaining business use
- Calculations supporting any apportionment
Why are records particularly important for mixed-use expenses?
If an expense is partly personal, the receipt alone may not explain how you calculated the business element.
For example, if you claim a proportion of your home internet cost, keeping a note of the method used to determine the business proportion can make the calculation easier to understand later.
Similarly, for business mileage, recording journeys when they happen is much easier than trying to reconstruct an entire year’s travel from memory.
Good records also make it easier for your accountant to prepare accurate accounts and tax returns.
A Simple Test Before Claiming a Business Expense
Before including an expense in your accounts, ask yourself five questions:
| Question | What to consider |
|---|---|
|
What did I pay for?
|
Identify the actual goods or service rather than relying on a vague bank statement description.
|
|
Why did the business incur the cost? |
Consider the genuine purpose of the expenditure.
|
|
Is there any private use?
|
If the cost has both business and personal elements, check whether an adjustment or apportionment is required.
|
|
What tax rules apply?
|
Different types of expenditure can have different rules. Equipment, travel, finance costs and home-working expenses should not automatically be treated in the same way.
|
|
Can I prove the expense?
|
Keep the invoice, receipt or other evidence needed to support the amount and business purpose.
|
This simple process can prevent many common expense-claim errors.
The Key Point About Small Business Expenses
There is no benefit in trying to claim every cost that has some connection with your business.
The better approach is to identify the costs your business is genuinely entitled to claim, apply the relevant tax rules and keep appropriate evidence.
For straightforward expenses, this may be relatively simple. For mixed-use costs, equipment, travel, home working and other areas with specific rules, it is worth taking a closer look before including the expense in your tax calculation.
The final part of this guide looks at how expense rules can differ between sole traders and limited companies, how simplified expenses work, common mistakes to avoid and some of the questions small business owners ask most often.
Sole Trader vs Limited Company: Does the Treatment of Expenses Differ?
Yes.
This is one of the most important points for small business owners.
A sole trader calculates taxable trading profits for Income Tax purposes, while a limited company calculates its taxable profits for Corporation Tax.
The same purchase can therefore require different treatment depending on who incurred the cost and how the business operates.
For limited companies, HMRC distinguishes between revenue and capital expenditure and says deductible revenue expenses generally need to be incurred wholly for a business purpose. Certain expenses are specifically disallowed.
Limited companies may also need to consider:
- Benefits in kind
- Director expenses
- Capital allowances
- Company-paid personal expenses
- Employee expenses
- Corporation Tax treatment
For that reason, do not assume that a rule applying to a sole trader automatically applies to a limited company.
If you’re deciding between the two structures, it is better to examine the tax and administrative differences separately rather than trying to apply one set of expense rules to both.
Common Small Business Expense Mistakes
Even when an expense appears to be business-related, mistakes can happen when the rules are applied incorrectly.
Here are some of the most common areas to watch.
1. Claiming private expenses as business costs
Paying for something from a business bank account does not automatically make it an allowable business expense.
If an expense is genuinely private, it should not simply be claimed because the business owner paid for it.
Where an identifiable business element can be separated from a private element, the relevant rules may allow the business portion to be considered.
2. Assuming every business purchase is an immediate expense
Some purchases are capital rather than ordinary revenue expenses.
For example, a business purchasing a long-term asset may need to consider capital allowances or other capital rules rather than simply deducting the full purchase price as an ordinary expense.
This can be particularly relevant for:
- Computers
- Machinery
- Vehicles
- Specialist equipment
- Business premises
Limited companies also need to distinguish between revenue and capital expenditure when calculating Corporation Tax.
3. Claiming the full cost of mixed-use expenses
If something has both business and private use, don’t automatically claim the entire amount.
This can apply to:
- Mobile phones
- Internet
- Vehicles
- Computers
- Home-working costs
- Other assets or services
The correct treatment depends on the expense and the applicable rules. Where an identifiable business proportion can properly be separated, that portion may be deductible.
4. Treating commuting as business travel
A journey being made because you are going to work does not automatically make it a business journey.
Travel between home and a permanent workplace can be treated differently from qualifying business travel, such as travelling to a client or another qualifying business location.
This is one reason why keeping a mileage log that records the destination and business purpose of each journey is useful.
5. Assuming every meal is a business expense
Buying lunch during a normal working day does not automatically make the cost deductible.
Food and drink can become relevant in certain qualifying business-travel situations, but the rules are not the same as simply claiming your normal everyday meals.
If you regularly incur travel and subsistence costs, check the rules that apply to your particular circumstances before claiming them.
6. Using simplified expenses without checking if they are suitable
Simplified expenses can make record keeping easier, but they are not automatically the best option for every business.
For example, a business with relatively high actual vehicle or home-working costs may want to compare the simplified method with the actual-cost method.
HMRC’s simplified-expenses checker can help eligible sole traders and partnerships compare the approaches.
7. Keeping incomplete records
A bank statement showing a payment is not always enough to explain what the expense was for.
Where possible, retain:
- Invoices
- Receipts
- Contracts
- Mileage records
- Business-use calculations
- Insurance documents
- Subscription records
- Other supporting evidence
Good records make it easier to prepare accurate accounts and explain expense claims later.
How Can an Accountant Help With Business Expenses?
Business expenses may appear straightforward when considered individually, but the overall picture can become more complicated as a business grows.
An accountant can help you:
- Identify potentially allowable business expenses
- Separate business and personal costs
- Review mixed-use expenses
- Understand capital versus revenue expenditure
- Consider whether simplified expenses are appropriate
- Maintain accurate bookkeeping records
- Prepare accounts and tax returns
- Review expense policies for directors and employees
- Identify areas where your current record keeping could be improved
The purpose of professional advice is not to find ways to claim every possible expense. It is to help make sure that legitimate expenses are identified, treated correctly and supported by appropriate records.
If you’re looking for professional support, our Small Business Accountants in London can help with bookkeeping, accounts and tax compliance.
Frequently Asked Questions About Small Business Expenses
Can a small business claim expenses?
Yes, a small business may be able to claim qualifying costs incurred for business purposes, subject to the tax rules that apply to the business and the particular expense. The rules are different depending on whether you operate as a sole trader, partnership or limited company.What expenses can a sole trader claim?
A sole trader may be able to claim qualifying costs such as office expenses, software, professional fees, insurance, business travel, certain home-working costs, equipment and other expenses incurred for the business. The expense must meet the relevant rules, and private expenditure cannot simply be treated as a business cost.Can a limited company claim business expenses?
Yes. A limited company can generally deduct qualifying business costs when calculating its taxable profits for Corporation Tax, provided the expenditure is allowable and not specifically disallowed. Companies also need to consider whether an expense is revenue or capital expenditure.Can I claim expenses if I work from home?
If you are self-employed, you may be able to claim qualifying home-working costs using either actual-cost calculations or the simplified-expenses method, if eligible. The simplified method is based on the number of hours worked from home each month. The rules can be different for employees and directors, so it is important to establish whether you are claiming as a self-employed business or in another capacity.Can I claim my business phone bill?
Potentially, yes. If a phone or internet service is used for both business and personal purposes, you need to consider the business element under the applicable rules. If the service is used entirely for business, the treatment may be more straightforward.Can I claim mileage for business journeys?
Eligible self-employed businesses may be able to use HMRC’s simplified mileage rates for qualifying business journeys. For 2026/27, the rate for cars and goods vehicles is 55p per mile for the first 10,000 business miles and 25p thereafter. Motorcycles have a rate of 24p per mile. The rules and available methods depend on the circumstances, so accurate mileage records are important.Can I claim the cost of a laptop for my business?
A laptop used for business may qualify for tax relief, but the treatment can depend on the business structure, accounting method, whether the purchase is capital expenditure and whether there is private use. A high-value computer should therefore not automatically be treated in exactly the same way as a routine office expense such as stationery.Can I claim accountancy fees?
Business-related accountancy and professional fees can potentially qualify as allowable expenses where the relevant conditions are met. For self-employed businesses, HMRC specifically identifies certain accountancy, legal and professional fees incurred for business reasons as allowable. However, there are exceptions, including certain costs relating to preparing and submitting a Self Assessment tax return.Can I claim meals as a business expense?
Not simply because you were working. Normal personal meals are generally different from food and drink costs incurred in qualifying business-travel circumstances. The nature of the journey and the circumstances of the expense need to be considered before claiming it.What business expenses cannot I claim?
You cannot simply claim private expenditure or costs that do not meet the relevant tax rules. Examples that may be disallowed or restricted include certain private expenses, ordinary commuting, fines and penalties, and certain personal or non-business costs. The exact treatment depends on the expense and the circumstances.Key Takeaways
Understanding business expenses is not about finding the biggest possible deduction. It is about identifying genuine business costs and applying the correct tax treatment.
Before claiming an expense, consider:
- What was the expense for?
- Was it genuinely incurred for the business?
- Is it revenue or capital expenditure?
- Is there any private use?
- Does a specific tax rule apply?
- Do you have records to support the claim?
For sole traders and qualifying partnerships, simplified expenses can provide an alternative way of calculating certain vehicle, home-working and business-premises costs. Limited companies cannot use the simplified-expenses rules in the same way.
When an expense is unusual, significant or has both business and personal elements, checking the relevant rules before claiming it can help prevent mistakes.
Final Thoughts: Getting Your Business Expenses Right
Business expenses are a normal part of running a small business, but not every cost connected with your work is automatically tax deductible.
The safest approach is to keep clear records, understand the distinction between business and personal expenditure, and apply the rules that relate to your particular business structure.
If you are a sole trader, freelancer, contractor or limited company director and are unsure whether a particular cost can be claimed, getting professional advice can help you avoid both overclaiming and missing legitimate deductions.
For businesses that want ongoing help with bookkeeping, accounts and tax compliance, our Small Business Accountants in London can provide tailored support.
Need help reviewing your business expenses? Contact our team to discuss your accounting and tax requirements.